IAS 34 sets the minimum content and the recognition and measurement principles for an interim financial report prepared in accordance with IFRS Accounting Standards. It permits either a complete set of financial statements or a condensed set with selected explanatory notes. In both cases, the report must be built on the same underlying recognition and measurement principles as annual IFRS financial statements, subject to the specific interim requirements in IAS 34.
For CFOs, controllers and senior fund-finance teams, the difficult work lies beyond shortening the annual report. The reporting team must identify the correct comparative periods, update year-to-date measurements, reassess estimates, calculate interim tax, capture significant events and preserve enough evidence for review and approval within a compressed timetable.
When IAS 34 applies
An interim period is a financial reporting period shorter than a full financial year. The IFRS Foundation’s IAS 34 overview explains that IAS 34 does not decide which entities must publish interim reports, how frequently they must report or how quickly a report must be issued. Those matters generally arise from local law, securities regulation, stock-exchange rules, financing arrangements or an entity’s own decision.
IAS 34 applies when an entity that uses IFRS Accounting Standards in its annual financial statements publishes an interim financial report that asserts compliance with IFRS Accounting Standards. A voluntary financial update does not automatically become IAS 34-compliant simply because it covers a period shorter than a year. If the report is described as complying with IFRS Accounting Standards, it must comply with all applicable IFRS requirements, including IAS 34, and state that it complies.
Each annual or interim report is assessed on its own. Failure to publish an IAS 34-compliant interim report does not, by itself, prevent the annual financial statements from complying with IFRS Accounting Standards.
Complete or condensed interim financial statements
An entity may publish:
- A complete set of financial statements, whose form and content follow the requirements applicable to a complete annual set.
- Condensed financial statements containing the minimum components required by IAS 34 and selected explanatory notes.
A condensed report is not simply the annual financial statements with fewer pages. It must include, at a minimum:
- A condensed statement of financial position.
- A condensed statement or statements of profit or loss and other comprehensive income.
- A condensed statement of changes in equity.
- A condensed statement of cash flows.
- Selected explanatory notes.
Under paragraph 10 of IAS 34, each condensed statement includes at least the headings and subtotals presented in the most recent annual financial statements. Additional line items and notes are included when their omission would make the condensed interim financial statements misleading. Comparative periods are governed separately by paragraph 20.
Where an entity is within the scope of IAS 33 Earnings per Share, basic and diluted earnings per share for the interim period are presented in the statement that presents the components of profit or loss.
Which comparative periods are required?
IAS 34 requires the following periods for condensed or complete interim financial statements:
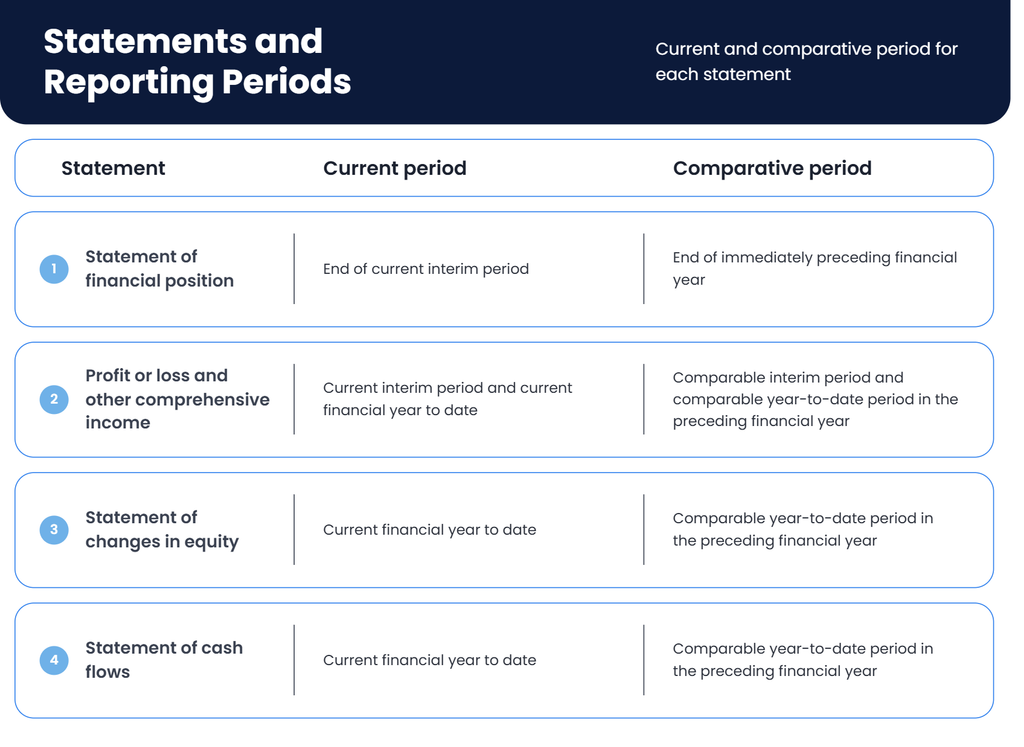
An entity whose business is highly seasonal is encouraged to disclose financial information for the 12 months ending on the interim reporting date and comparative information for the preceding 12-month period. This additional information does not replace the required interim periods.
If an entity publishes a complete set of interim financial statements, other presentation requirements may result in additional statements or comparatives. The reporting team should therefore confirm at the outset whether the report is complete or condensed and which version of the presentation requirements applies.
Recognition and measurement are year to date
IAS 34 requires the same accounting policies as the annual financial statements, except for a policy change made after the latest annual statements that will be reflected in the next annual statements. Reporting frequency must not affect measurement of the annual results. To achieve that outcome, interim measurements are made on a year-to-date basis.
This has practical consequences:
- An asset must meet the applicable recognition criteria at the interim date rather than being recorded in anticipation of qualifying by year end.
- A liability must represent an obligation at the interim date.
- A cost that would not qualify as an asset at year end is not deferred at an interim date to smooth earnings.
- A revised estimate affects the current year-to-date measurement rather than causing prior interim statements to be retrospectively adjusted.
Significant changes in estimates are disclosed. If an estimate reported in an earlier interim period changes significantly during the final interim period and the entity does not publish a separate report for that final period, IAS 34 requires the nature and amount of the change to be disclosed in the annual financial statements.
Seasonal, cyclical and occasional items
Revenue received seasonally, cyclically or occasionally is not anticipated or deferred at an interim date if that treatment would be inappropriate at year end. Costs incurred unevenly during the year are anticipated or deferred only when that treatment would also be appropriate at year end.
This prevents an entity from smoothing results merely because the reporting period is shorter. It does not remove the need to explain material seasonality or unusual movements in the notes.
Greater use of estimates
IAS 34 recognises that interim reporting generally requires greater use of estimation methods than annual reporting. The aim remains to produce reliable information. Preparers should update material estimates using information available when the interim statements are prepared and retain the assumptions, source data, review evidence and sensitivity analysis appropriate to the item.
For funds and other investment structures, this may include evidence supporting fair-value measurements, expected credit losses, fee accruals, carried-interest or performance-related estimates where applicable, and the completeness of investment and cash populations. The applicable accounting follows the relevant IFRS Accounting Standard; IAS 34 governs the interim reporting context rather than replacing that underlying Standard.
Interim income tax
IAS 34 requires income tax expense in each interim period to be recognised using the best estimate of the weighted-average annual income tax rate expected for the full financial year. The estimate is applied on a year-to-date basis and updated at subsequent interim dates when expectations change.
The calculation can be more complex than applying one percentage to group profit before tax. Different tax jurisdictions, categories of income, enacted or substantively enacted rate changes, losses, credits and one-off items may require separate consideration under IAS 12 and the IAS 34 application guidance. The tax calculation should reconcile to the underlying forecasts and identify which items are included in the estimated annual effective rate and which are recognised discretely.
Impairment at an interim date
The same recognition and measurement principles used at year end apply when an impairment indicator exists at an interim date. An entity cannot postpone an impairment assessment because an annual valuation will be performed later.
The subsequent accounting also matters. IFRIC 10 Interim Financial Reporting and Impairment states that an impairment loss recognised for goodwill in a previous interim period is not reversed. Other reversals follow the requirements of the applicable Standard. The review file should identify the asset, trigger, valuation date, methodology, assumptions, approval and any restriction on later reversal.
Materiality in an interim report
Materiality is assessed in relation to the interim-period financial data. An item that may appear small against expected full-year results can still be material to the interim report because of its size, nature or effect on the period’s trends and judgements.
The IFRS Practice Statement on materiality is non-mandatory guidance, but it provides a useful framework for making materiality judgements, including in interim reporting. It does not replace the requirements of IAS 34 or other IFRS Accounting Standards.
Selected explanatory notes
The selected notes explain events and transactions that are significant to understanding changes in financial position and performance since the end of the latest annual reporting period. They update the annual report rather than repeating unchanged information.
Depending on the facts and applicable Standards, the notes may need to address:
- A statement that the same accounting policies and methods of computation have been followed, or a description of changes.
- Seasonality or cyclicality.
- Unusual items affecting assets, liabilities, equity, profit, loss or cash flows.
- Significant changes in estimates.
- Issuances, repurchases and repayments of debt and equity securities.
- Dividends paid.
- Segment information where IFRS 8 applies.
- Significant events after the interim period.
- Changes in the composition of the entity, including business combinations, loss of control and restructurings.
- Changes in contingent liabilities or contingent assets.
- Specified fair-value information for financial instruments.
- Revenue disaggregation required by IFRS 15.
- Other significant events such as inventory write-downs, impairment losses, litigation settlements or material capital commitments.
The list is not a generic disclosure checklist. Each requirement has its own scope and materiality considerations. Disclosures required by paragraph 16A are normally presented on a financial-year-to-date basis.
Information may be incorporated by cross-reference to another statement, such as a management commentary or risk report, when IAS 34’s conditions are met and users have access to that information on the same terms and at the same time. The cross-referenced information forms part of the interim financial report.
IFRS 18 and interim reporting from 2027
IFRS 18 Presentation and Disclosure in Financial Statements is effective for annual reporting periods beginning on or after 1 January 2027, with earlier application permitted. It replaces IAS 1 and amends IAS 34.
When IFRS 18 is applied, condensed interim financial statements include the required information about management-defined performance measures. Transition also affects interim presentation and comparative reconciliations in the first year of application. Until an entity applies IFRS 18, those amendments are issued requirements rather than mandatory current-period treatment.
The reporting timetable should therefore identify the entity’s IFRS 18 adoption date, its effect on annual headings and subtotals, the measures used in public communications and the data needed for interim disclosures and transition reconciliations.
A controlled interim reporting process
The shorter timetable makes ownership and evidence especially important.
Confirm scope and reporting basis
Document why the report is being prepared, the applicable legal or market deadline, whether it will assert IFRS compliance and whether it is complete or condensed. Confirm the current and comparative periods before opening the close.
Allocate preparation, review and approval
Assign owners for each statement, note, estimate and consolidation adjustment. Define who prepares the work, who performs the technical and numerical review, who resolves exceptions and who approves release.
Reconcile complete data
Reconcile ledgers, administrator files, bank and custody records, investment data and consolidation submissions. Track late or missing data and document any controlled estimate or alternative procedure used before final information becomes available.
Update estimates and judgements
Maintain an estimate register covering tax, fair values, impairments, provisions, expected credit losses and other material judgements. Record the information available at the reporting date, changes from the annual position and the effect on current year-to-date results.
Build the disclosure record
Use a disclosure checklist calibrated to the entity’s activities and applicable Standards. Link each material movement or event to the proposed statement or note disclosure, the supporting evidence and the reviewer conclusion.
Manage exceptions and failure response
Set escalation routes for unreconciled balances, valuation delays, control failures and unresolved technical matters. If a key system or provider fails, document the fallback procedure, its limitations, the additional review performed and any effect on the reporting timetable.
Retain client oversight
Where preparation is outsourced or co-sourced, management remains responsible for accounting policies, judgements, controls and approval of the financial statements. Service reporting should make open items, late inputs, review points and missed deadlines visible.
Applying IAS 34 in complex finance operations
We supports the funds and finance industry through fund administration support, operational finance outsourcing, specialist project support and professional secondments. Within an agreed scope, that support can provide additional execution capacity for reconciliations, close schedules, working papers and reporting processes within the client’s systems and controls.
Management and its appointed technical advisers remain responsible for determining the applicable reporting obligations, approving accounting conclusions and asserting compliance with IFRS Accounting Standards. Audit or review requirements are separate from IAS 34 and depend on the relevant jurisdiction, market rules and engagement terms.
The practical conclusion
An IAS 34 report is an update to the latest annual financial statements, but it remains a financial report in its own right. The entity must use the correct periods, apply year-to-date measurement, update estimates, identify material events and retain evidence for every significant conclusion.
The strongest interim processes connect the close timetable, technical accounting, disclosure review and governance approval. That approach produces a report that is timely without weakening the accounting work behind it.
Frequently Asked Questions
No. IAS 34 does not determine who must report or how often. Local law, regulators, stock exchanges or other requirements may impose an obligation. IAS 34 applies when an interim report is prepared in accordance with IFRS Accounting Standards and asserts that compliance.
No. A condensed interim report focuses on significant changes since the latest annual report, while still providing the minimum components and selected notes required by IAS 34 and other applicable Standards. A complete interim set follows the requirements for complete financial statements.
IAS 34 measurements are made on a year-to-date basis so that reporting frequency does not affect annual results. The statement of profit or loss and other comprehensive income may also present the current interim period when the entity reports more frequently than half-yearly.
No. IFRIC 10 prohibits reversal of an impairment loss recognised for goodwill in a previous interim period, even if a later assessment would have avoided the loss had it been made only at year end.